
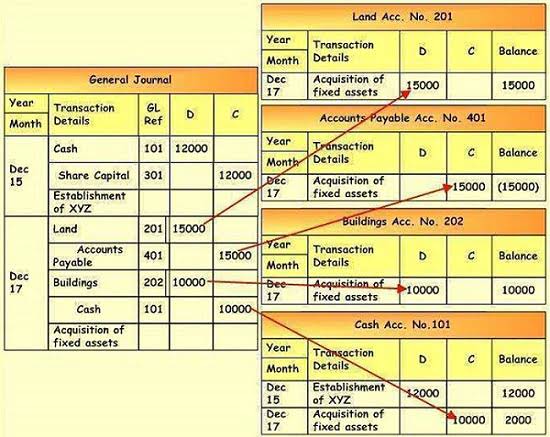
For instance, imagine that your company has a new job coming up, and you need to calculate predetermined overhead rate for an estimate of manufacturing costs. Predetermined overhead rates are also used in the budgeting process of a business. As discussed above, a business must wait until the end of a period to know the actual performance in terms of overheads incurred. However, since budgets are made at the start of the period, they do not allow the business to use actual results for planning or forecasting.
- The predetermined overhead rate is calculated by dividing the estimated manufacturing overhead by the estimated activity base (direct labor hours, direct labor dollars, or machine hours).
- Hence, this predetermined overhead rate of 66.47 shall be applied to the pricing of the new product VXM.
- Before jumping to detail, let’s go through the basic overview and key definition first.
- Both under-absorption and over-absorption are common issues that are typically dealt with at year-end when actual totals are available.
- Despite the fact that it may become more complex, it is considered more accurate and helpful to have different predetermined overhead rates for each department, because the level of efficiency and precision increases.
Computing Actual Overhead Costs
As a result, there is a high probability that the actual overheads incurred could turn out to be way different than the estimate. Because the entire manufacturing process is automated, Vision’s CFO decides to use machine hours as the basis for the overhead allocation rate or absorption. For example, the recipe for shea butter has easily identifiable quantities of shea nuts and other ingredients.
Sales and production decisions based on this rate could be faulty
The company also expects to pay $200 for rent, $150 for maintenance, and $50 for coffee. There are a lot of ways that you can reduce overhead costs that will make a positive impact on your business. And because overhead rates are an estimate, if the numbers you’re accessing to calculate your overhead rate aren’t accurate, then the results will Oil And Gas Accounting be inaccurate as well.
Setting pricing
While predetermined overhead rates are widely used and needed for businesses, they may have some limitations. A business needs to estimate its total overheads for a period and estimate its total units or activity basis for the predetermined overhead rates. If these estimates are predetermined oh allocation rate not accurate, they can end up causing a lot of problems for the business specially if decisions are based on the rates, such as pricing decisions. However, for most businesses waiting until the product has been produced to determine its costs may not be an option. The material and labor costs are easy to predict as these can be calculated using estimated usage of material and labor per product multiplied with the expected rate of usage per unit of the product. However, the business may face problems when trying to determine the overhead cost per unit.
Computing a Predetermined Overhead Rate
- Create a Full Dynamic Financial Model in 2 Days (6 hours)
- Take, for instance, a manufacturing company that produces gadgets; the production process of the gadgets would require raw material inputs and direct labor.
- After reviewing the list, you’ll see that while the costs are necessary for doing business, they are not directly related to production or services.
- By leveraging Flxpoint’s comprehensive platform, businesses can effectively reduce overhead costs, leading to improved profitability and operational efficiency.
- This means that if an actual overhead rate is used by the business, the costs of products manufactured in summer will be higher than cost of goods manufactured in the winter.
- When making pricing decisions about a product, the management of a business must first understand what the costs of the product are.
This is why a predetermined overhead rate is computed to allocate the overhead costs to the production output in order to determine a cost for a product. The predetermined overhead rate is, therefore, usually used for contract bidding, product pricing, and allocation of resources within a company, based on each department’s utilization of resources. This calculator offers a straightforward way to estimate the predetermined overhead rate, making it easier for businesses to manage and allocate their manufacturing overhead costs effectively. Enter the total manufacturing overhead cost and the estimated units of the allocation base for the period to determine the overhead rate. Big businesses may actually use different predetermined overhead https://techstreamline.org/understanding-employment-taxes-internal-revenue-2/ rates in different production departments, as these may vary significantly.
The rent in Atlanta isn’t the same as Chicago, and your overhead rate should reflect that. (b) Alternatively, we use machine hour rate if in the factory or department of the production is mainly controlled or dictated by machines. Get an overview of the statement of cash flows, which show cash sources and uses during a specific period of time.
In more complicated cases, a combination of several cost drivers may be used to approximate overhead costs. Once you’ve calculated your overhead costs for a specified time frame, you’re ready to complete the overhead rate calculation. In these situations, a direct cost (labor) has been replaced by an overhead cost (e.g., depreciation on equipment).
Multiple or departmental predetermined overhead rates:
It’s particularly useful in scenarios where indirect costs are significant and need to be fairly allocated across different products or services. Calculating the Predetermined Overhead Rate (POR) is a critical step in cost accounting, particularly in the manufacturing sector. It involves estimating the manufacturing overhead costs that will be incurred over a specific period and then allocating those costs to the units produced during that period. A predetermined overhead rate is defined as the ratio of manufacturing overhead costs to the total units of allocation. Notice that the formula of predetermined overhead rate is entirely based on estimates.
The overhead rate has limitations when applying it to companies that have few overhead costs or when their costs are mostly tied to production. Also, it’s important to compare the overhead rate to companies within the same industry. A large company with a corporate office, a benefits department, and a human resources division will have a higher overhead rate than a company that’s far smaller and with fewer indirect costs. Overhead costs are expenses that are not directly tied to production such as the cost of the corporate office. To allocate overhead costs, an overhead rate is applied to the direct costs tied to production by spreading or allocating the overhead costs based on specific measures. The POR is used to apply overhead costs to products or job orders, helping businesses to accurately price their products, manage budgets, and analyze cost behavior.
